India – A Bridge to Global Change
India has spent much of 2026 outside the centre of the global equity story. Markets have been dominated by the rapid expansion of artificial intelligence investment, exceptionally strong semiconductor earnings and renewed pressure from higher oil prices and global interest rates. Those forces have created a more challenging backdrop for India. As foreign investors reduced exposure, the rupee weakened and India lagged both emerging market peers and many global asset classes.
Yet market performance has contrasted sharply with a domestic economy, which has continued to deliver. Growth continues to surprise positively, corporate earnings are recovering, macroeconomic balances have strengthened and policymakers have greater capacity to absorb external shocks than in previous cycles.
The resulting disconnect between market performance and domestic fundamentals is central to the opportunity we see today.
A challenging global backdrop
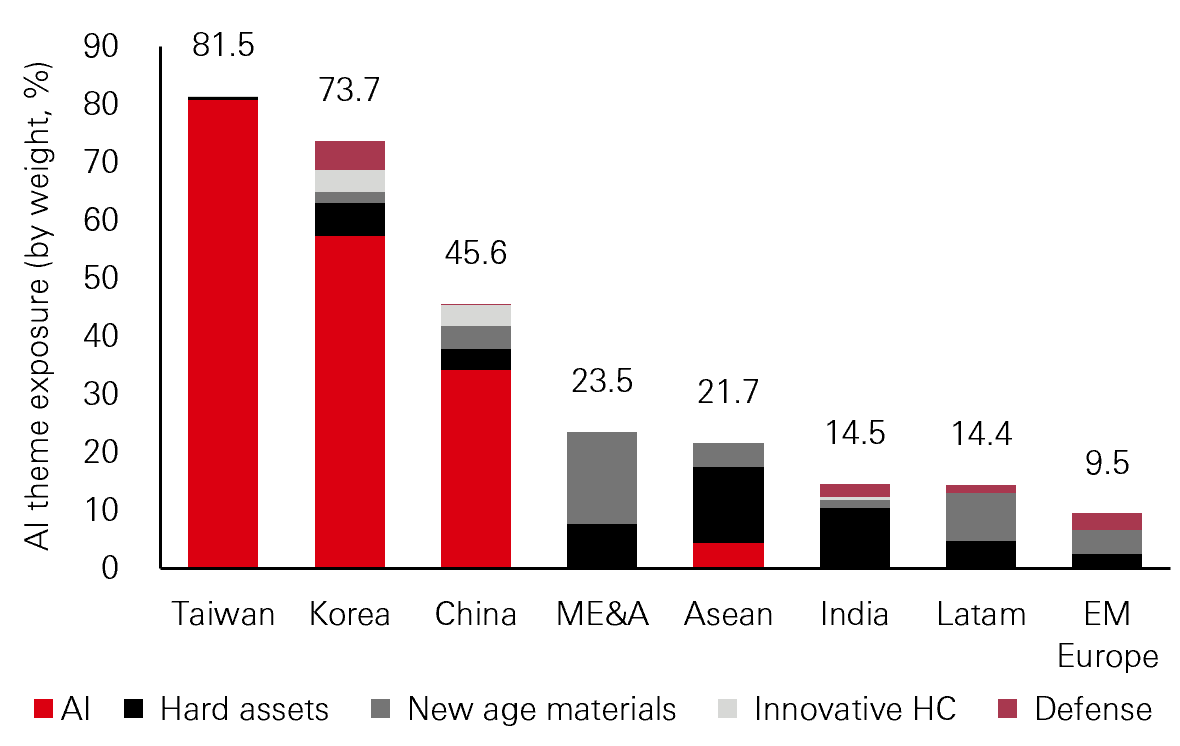
Three forces have shaped the market environment this year. The first is the energy shock. India remains a major oil importer, so higher crude prices affect the trade balance, inflation outlook and currency. The second is the rise in global interest rates and bond yields, which has put pressure on emerging market currencies and encouraged international investors to favour markets with either higher yields or more direct exposure to the prevailing growth themes. The third is the AI investment boom. Across Asia, earnings upgrades and equity returns have been unusually concentrated in semiconductor heavy markets. Korea and Taiwan have been among the clearest beneficiaries as global capital expenditure on compute, memory and AI infrastructure has accelerated. India, with a much smaller technology hardware weighting, has a larger share of financials, consumer businesses, healthcare and domestically oriented companies. AI related themes account for around 14.5 per cent of the Indian market, compared with more than 80 per cent in Taiwan and close to three quarters in Korea.
Rolling 12m trailing capex to end of quarter (US$ bn)
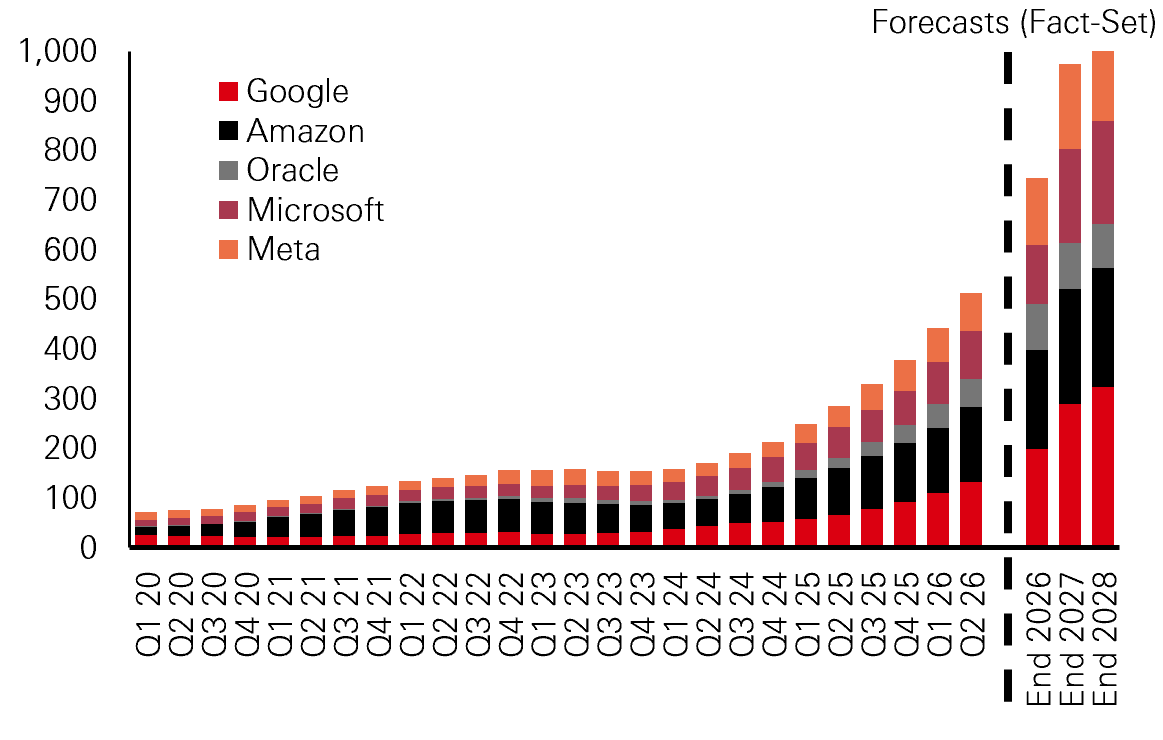
Click the image to enlarge
Source: Macrobond, Bloomberg, HSBC Asset Management, August 2026
AI theme exposure by market (%)
Click the image to enlarge
Source: Bloomberg, Jefferies, data as of September 2026
As a result, India has participated less in the extraordinary earnings acceleration generated by the AI capex cycle. Recent relative performance therefore reflects, in part, India’s different market composition rather than a deterioration in its domestic fundaments. The pressure is visible in eight consecutive weeks of relative underperformance — the longest in roughly 25 years — alongside a period of pronounced weakness relative to global asset classes. Foreign selling has also been substantial, even as domestic investors have continued to provide support.
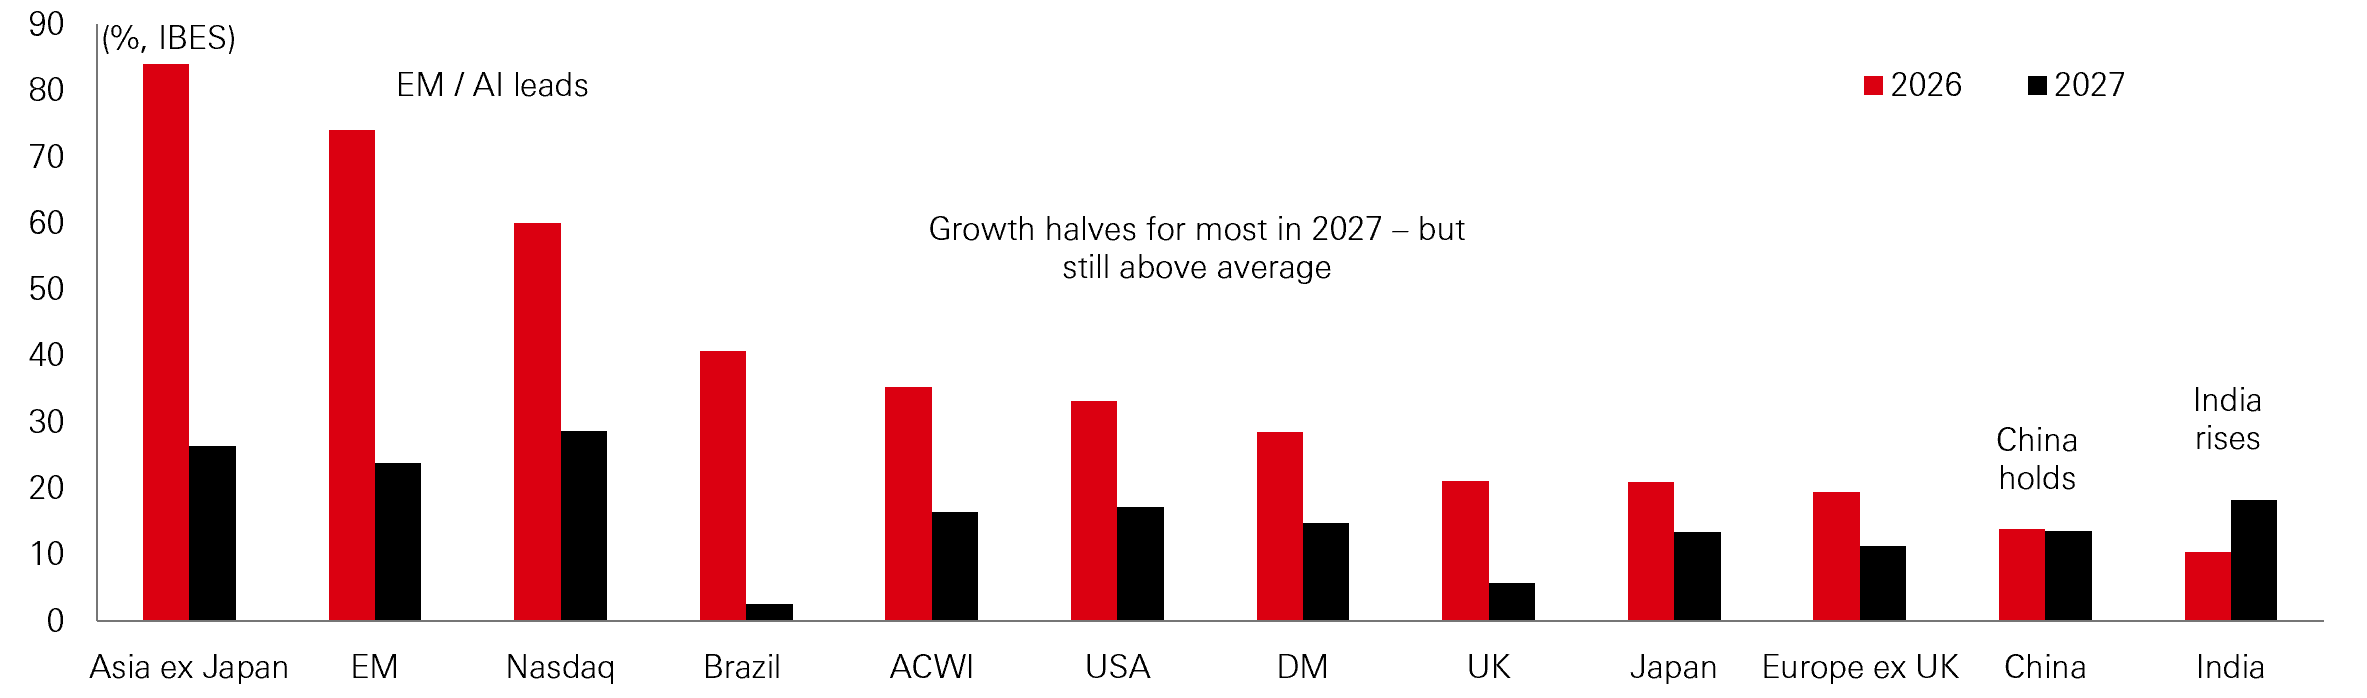
At the same time, India’s different sector composition provides diversification from the earnings drivers that have dominated markets this year. Indian equities are less dependent on continued increases in global semiconductor investment than those of several regional peers. That distinction could become increasingly valuable as the global earnings cycle becomes more balanced. Consensus expectations point towards a less extreme dispersion in 2027 with technology related earnings remaining strong, but growth moderates from exceptional levels while India’s profit trajectory becomes comparatively firmer.
Domestic momentum is strengthening
Against that backdrop, India’s macro data has held up well. Real GDP grew 7.8 per cent year-on-year in 1QFY27, ahead of expectations despite the energy price shock. Inflation has remained relatively contained despite the energy shock, and high frequency indicators such as cement consumption and electricity demand remain firm. The corporate earnings cycle is also improving, with the broad NIFTY 500 universe profit growth rebounding from -5.2 per cent year-on-year in 2QFY26 to 11.4 per cent in 1QFY27.
Nifty 500 sales (ex-OMC) up 8%
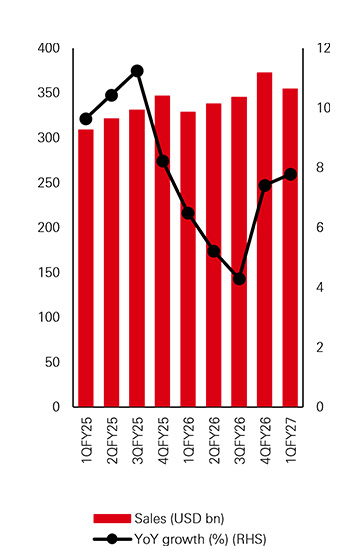
Click the image to enlarge
Nifty 500 EBITDA (ex-OMC) up 5%
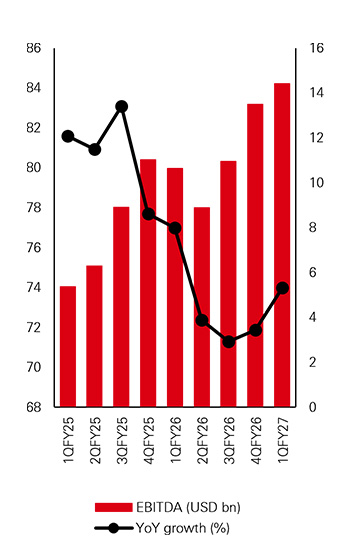
Click the image to enlarge
Nifty 500 PAT (ex-OMC) up 11%
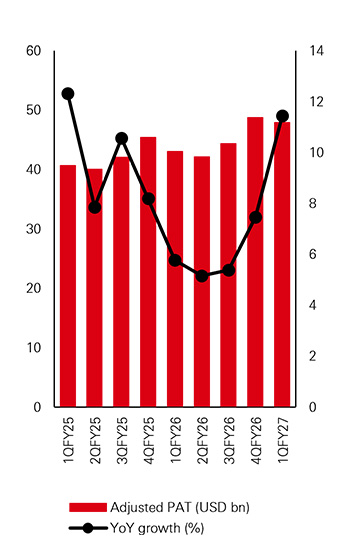
Click the image to enlarge
Source: Motilal Oswal Broking, Bloomberg, data as of September 2026
India also enters this period with stronger external buffers. Even with oil assumed at USD95/bbl, the current account deficit is estimated at around 1.6 per cent of GDP, remaining relatively contained compared with India’s own history. At the same time, foreign currency deposit inflows have strengthened the capital account and supported foreign exchange reserves, giving the Reserve Bank of India (RBI) greater capacity to manage periods of currency pressure and capital outflows.
Current account balance as % of GDP
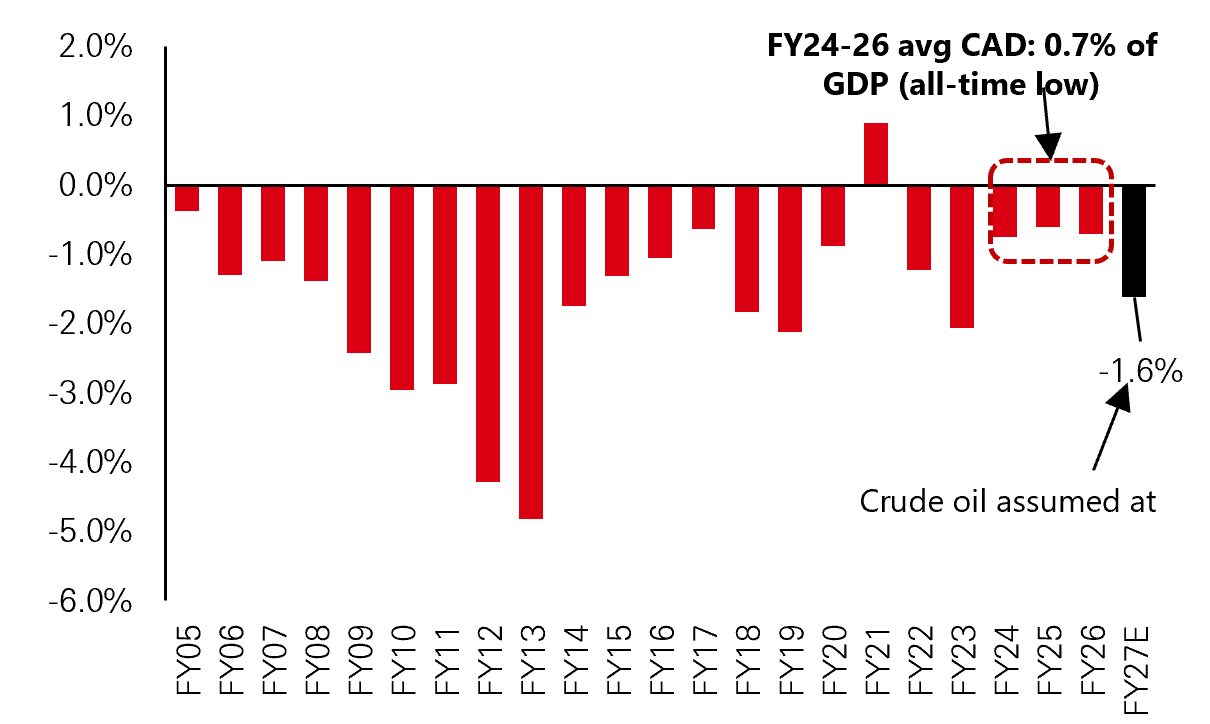
Click the image to enlarge
Capital account balance as % of GDP
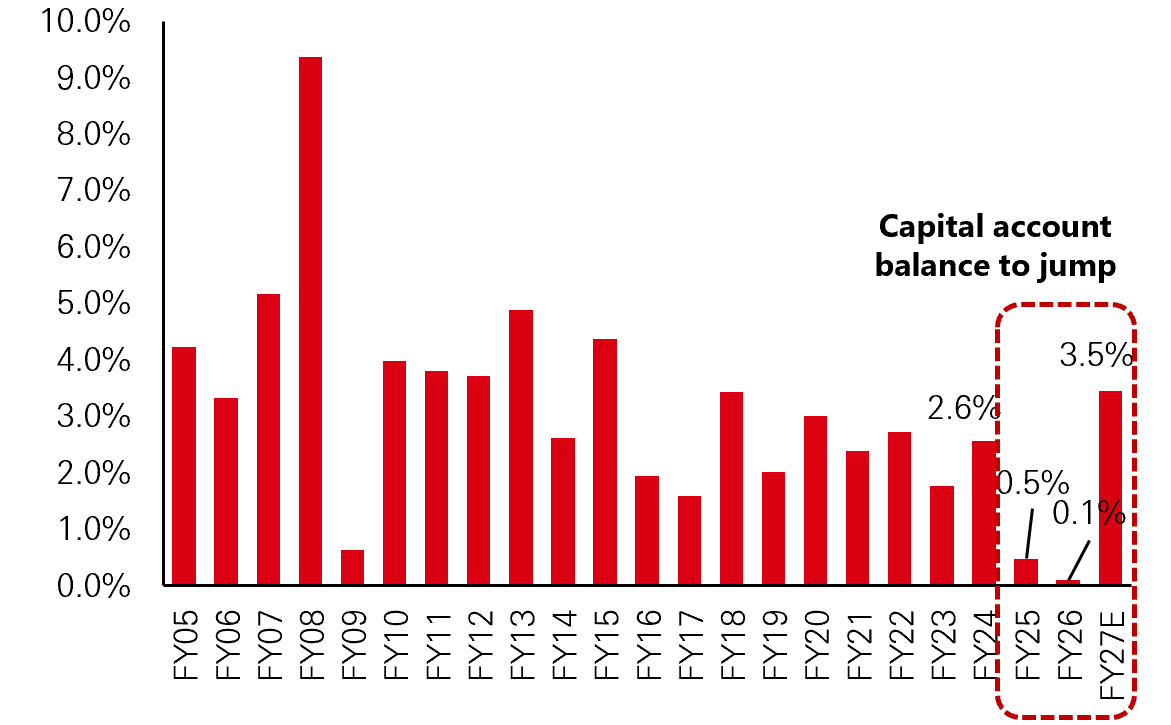
Click the image to enlarge
Stronger balance sheets provide India with an important source of resilience. The government has been reducing its fiscal deficit, while Indian corporates have spent much of the past decade deleveraging. That contrasts with several major developed economies, where fiscal positions have become more stretched. Together, these trends create greater capacity on both sides of the economy to absorb shocks while continuing to invest. During the recent energy shock, for example, the government had greater room to cushion households through changes in fuel taxation, rather than pass the full increase in energy costs directly to consumers.
India’s sensitivity to oil is also gradually changing. The economy is more services oriented, renewable energy is taking a larger share of incremental power generation, and electrification continues to reduce oil intensity. Oil consumption per unit of GDP has fallen from around 0.20 barrels per INR 10,000 of GDP in the late 1990s to around 0.116 today. Oil still matters, but its effect on domestic activity is less pronounced than in previous cycles.
New shock absorbers are emerging
One less conventional source of support comes from household wealth. Indian household gold holdings are estimated at around USD3.9 trillion, roughly double their value two years earlier. A growing gold loan market, with organised assets of around USD197 billion, also allows part of that wealth to be monetised, turning what has historically been a relatively passive store of value into an additional source of household liquidity.
While this does not replace wage growth or broader consumption fundamentals, it provides an additional buffer during periods of macroeconomic stress and adds to the resilience of household demand.
Value of gold held by Indian households
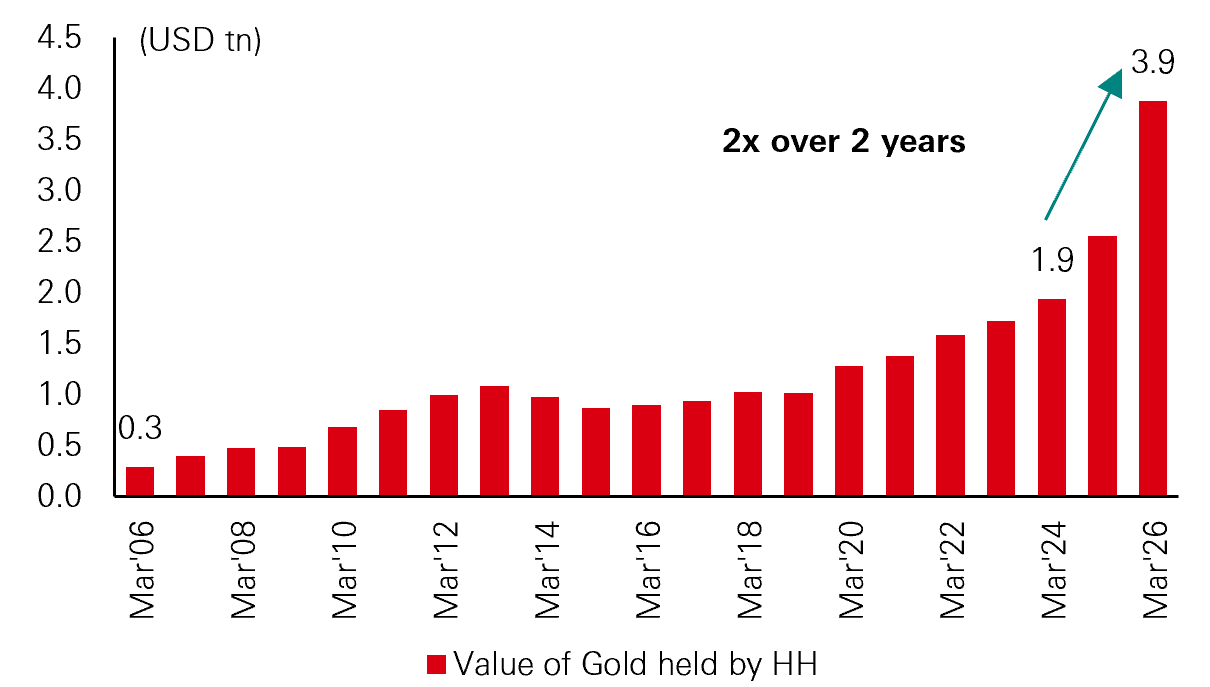
Click the image to enlarge
Capital account balance as % of GDP
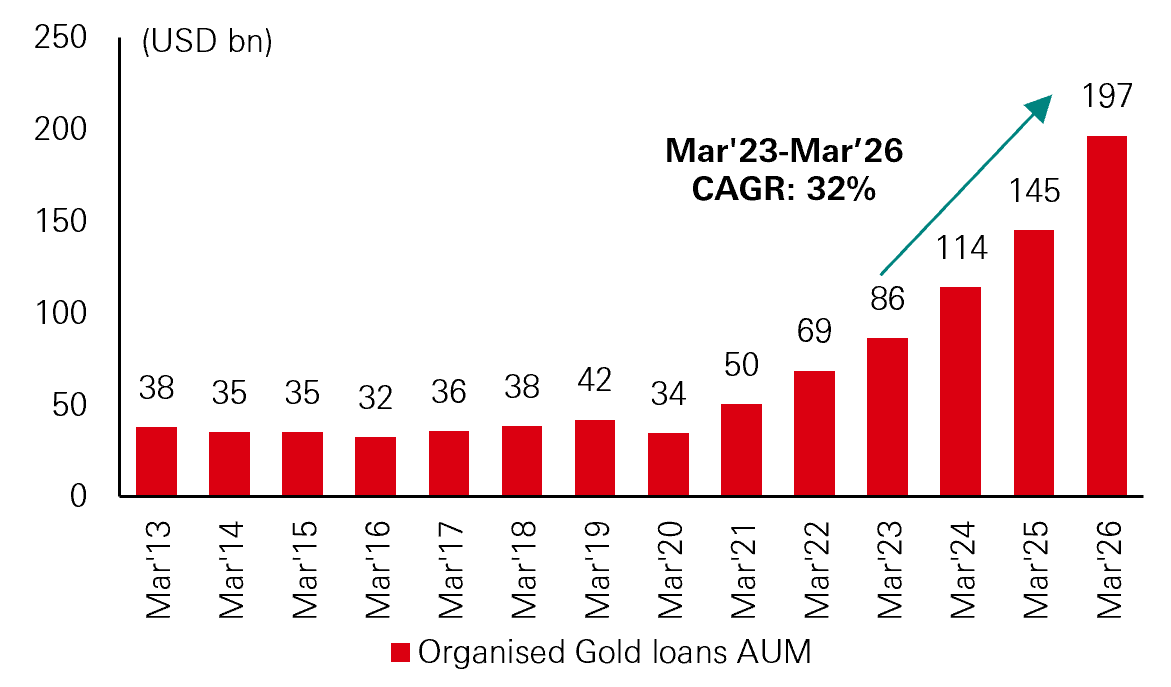
Click the image to enlarge
Source: RBI, Jefferies, Bloomberg, data as of September 2026
Relative valuations are becoming more supportive
Resilient fundamentals are increasingly being accompanied by a more supportive valuation starting point. India has historically traded at a premium to emerging markets, reflecting superior long-term growth, stronger returns on capital and a large domestic investor base. Following the recent period of underperformance and international tailwinds, India’s price-to-book valuation has moved below its own 10-year average - notable for a market that has historically commanded a sizeable premium. That premium has narrowed as investors crowded into exceptional AI related earning growth driven by capex.
On relative price-to-book measures, India has de-rated significantly versus emerging markets to its lowest level in roughly two decades. Its long run relative performance has also moved into territory that historically preceded stronger subsequent returns. While neither measure is a precise timing signal, taken alongside improving earnings and a more supportive macro backdrop, they point to a more attractive relative starting point.
Regional Premium / (Discount) to 10-year average on Price to Book
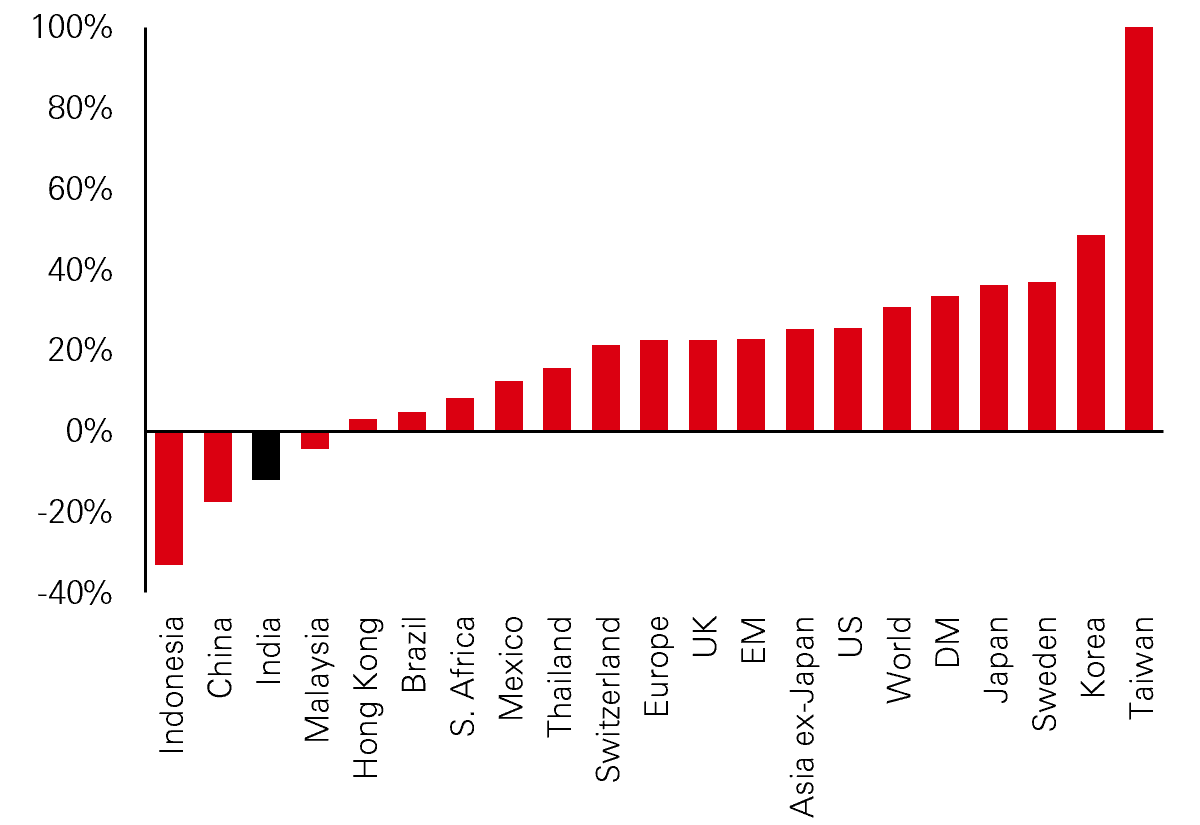
Click the image to enlarge
Source: MSCI, Refinitiv, HSBC Asset Management, 8 October 2026
Global FX valuation
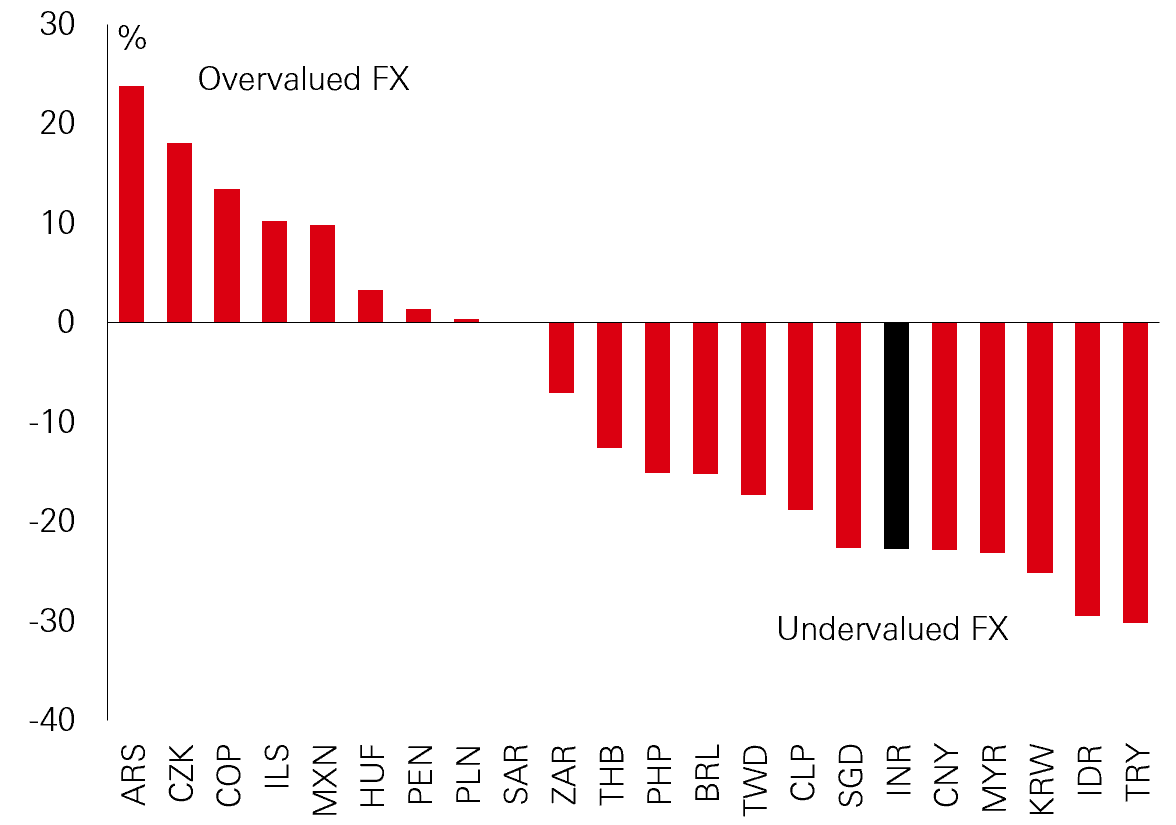
Click the image to enlarge
Source: Macrobond, Bloomberg, HSBC Asset Management, September 2026
The currency picture reinforces that assessment. After a period of depreciation, valuation models suggest the rupee has become increasingly inexpensive relative to its longer-term fundamentals. Meanwhile, Indian bond yields have been considerably more stable than the rise in US Treasury yields might suggest, providing another indication of resilience in India’s underlying macro fundamentals.
What could unlock the relative opportunity?
A more supportive valuation starting point becomes particularly relevant when accompanied by identifiable catalysts. The first potential catalyst is a moderation in the global forces that have worked against India. If oil prices stabilise and expectations for developed market rate increases become less aggressive, pressure on the rupee and foreign investor positioning could ease, allowing domestic fundamentals to play a larger role in market performance.
The second is an eventual broadening of the earnings cycle. The extraordinary profit growth currently concentrated in technology heavy markets is unlikely to accelerate indefinitely. Consensus expectations point to a more balanced earnings picture in 2027, with profit growth moderating in some of the largest AI beneficiaries while India’s earnings trajectory becomes comparatively firmer. The AI cycle does not need to reverse for this relative picture to improve; the gap between AI driven earnings growth and the rest of the market simply needs to narrow.
Global country EPS growth in 2026 and 2027
Click the image to enlarge
Source: Refinitiv, IBES, HSBC Asset Management, September 2026
This is particularly relevant because India offers a very different sector mix. As investors increasingly consider concentration and capital intensity within the global AI trade, India offers exposure to a broader set of earnings drivers rather than another geographic expression of the same cycle.
AI can still become part of India’s opportunity
Being relatively underexposed to AI hardware does not mean India is excluded from the technology cycle. The first stage of the global boom has rewarded the manufacturers of semiconductors, memory and computing hardware. The next phase could increasingly favour the deployment and adoption of that technology. India combines inexpensive data, a large digitally connected population and relatively low-cost power, while installed data centre capacity is expected to rise from around 1.3GW towards 10.5GW by FY31. Falling technology costs could therefore support adoption in much the same way that cheaper mobile data helped accelerate smartphone penetration.
Rising data center capacity in India (GW)
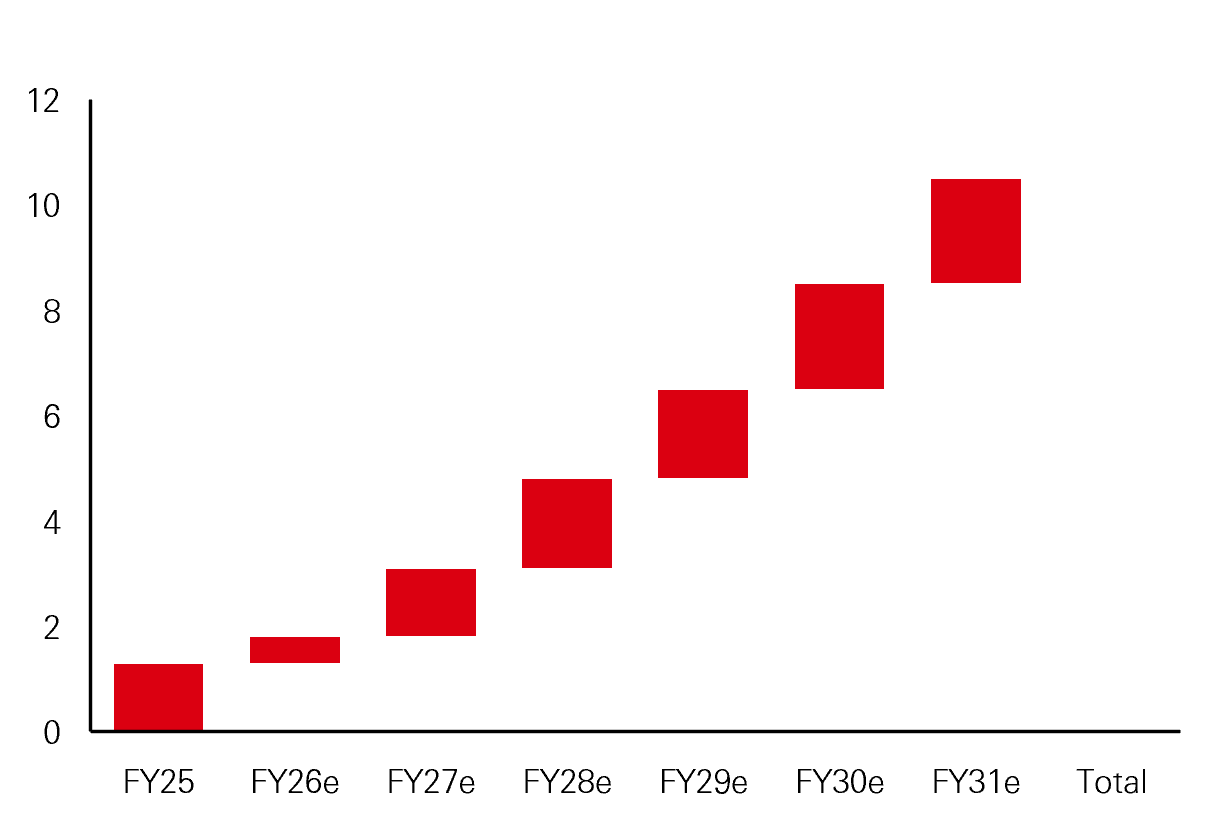
Click the image to enlarge
Source: Morgan Stanley estimates, HSBC Asset Management, June 2026
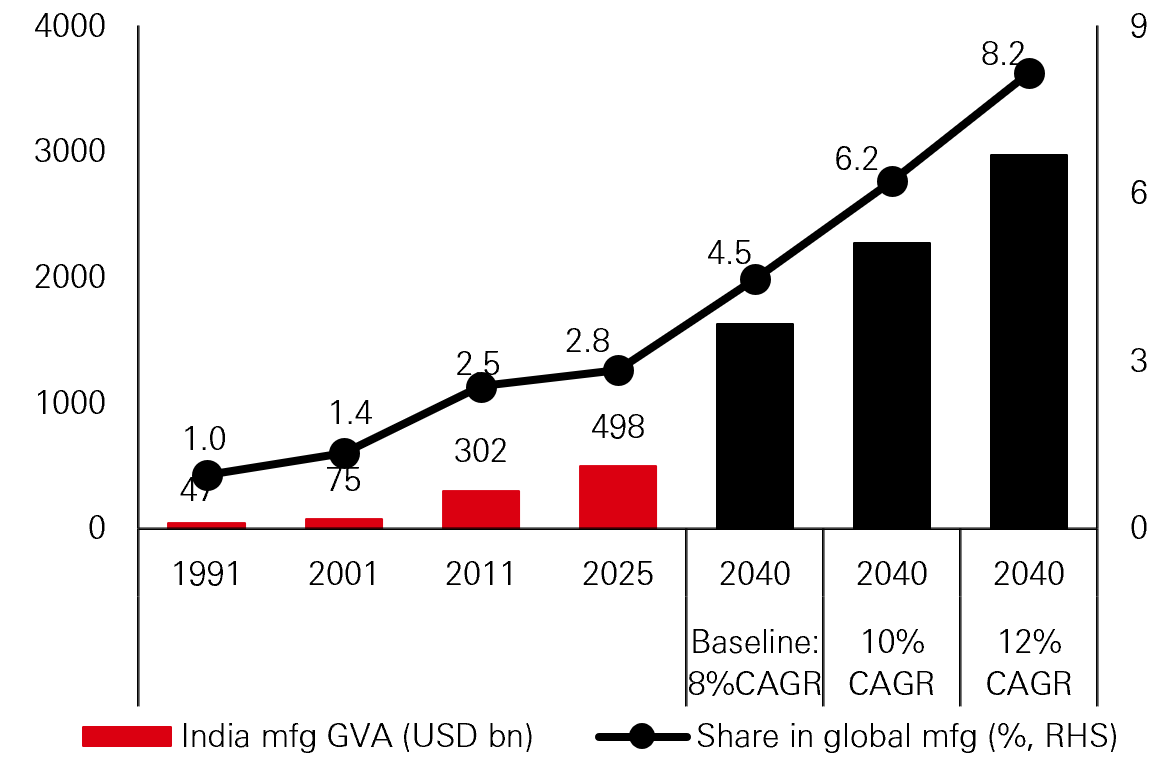
India’s manufacturing renaissance in progress
Click the image to enlarge
Source: BofA, UNIDO, September 2026
The opportunity extends beyond digital adoption. India is also seeking to capture a larger share of global manufacturing as supply chains diversify. Government incentives, shifting global supply chains and new trade agreements are encouraging investment in semiconductors, defence, critical minerals and other strategic industries. India currently accounts for around 2.8 per cent of global manufacturing, with manufacturing value added of close to USD500 billion, leaving considerable room for its share to expand as investment and supply chains broaden. A larger manufacturing base can deepen domestic supply chains, broaden employment, increase investment and complement India’s established strength in services.
Broadening, but a different role for India
India has faced an unusually challenging combination of higher oil prices and an AI led global capex cycle, but its investment case does not depend on either trend reversing. AI investment can remain strong while market leadership broadens. Oil prices can remain elevated while lower energy intensity and stronger external buffers reduce their impact. Global yields can stay higher while healthier domestic balance sheets support resilience.
What differentiates India is the composition of its growth. Markets that have benefited most from the current cycle which is increasingly concentrated in a narrow set of technology related earnings drivers. India offers something different: a broader sector mix, improving domestic earnings, stronger macro buffers and growing exposure to structural themes ranging from manufacturing to digital infrastructure. Recent relative underperformance has also improved the entry point. Foreign ownership is light, relative valuations have become more attractive and domestic investors continue to provide a stable source of capital.
For investors, the next stage of the global cycle may place greater value on diversified earnings growth, domestic resilience and structural investment themes that are less dependent on a single source of global capex. As market leadership broadens into 2027, those characteristics should give India a more differentiated role within global and emerging market portfolios.
Interested in exploring India’s investment opportunities?
If you have questions for our experts or would like to learn more about how you could access these opportunities, please get in touch with your HSBC Asset Management contact.
For more Investment Insights
For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector or security. The views expressed above were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and not guaranteed in any way. HSBC Asset Management accepts no liability for any failure to meet such forecast, projection or target. This document provides a high-level overview of the recent economic environment. It is for marketing purposes and does not constitute investment research, investment advice nor a recommendation to any reader of this content to buy or sell investments. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. Source: HSBC Asset Management, 30 September 2026.
Past performance does not predict future returns. Diversification does not ensure a profit or protect against loss. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector or security.
Important information
For Professional Clients and intermediaries within countries and territories set out below; and for Institutional Investors and Financial Advisors in the US. This document should not be distributed to or relied upon by Retail clients/investors.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. The performance figures contained in this document relate to past performance, which should not be seen as an indication of future returns. Future returns will depend, inter alia, on market conditions, investment manager’s skill, risk level and fees. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries and territories with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries and territories in which they trade.
The contents of this document may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. All non-authorised reproduction or use of this document will be the responsibility of the user and may lead to legal proceedings. The material contained in this document is for general information purposes only and does not constitute advice or a recommendation to buy or sell investments. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. We do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed herein are those of HSBC Asset Management at the time of preparation and are subject to change at any time. These views may not necessarily indicate current portfolios' composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients' objectives, risk preferences, time horizon, and market liquidity. Foreign and emerging markets: investments in foreign markets involve risks such as currency rate fluctuations, potential differences in accounting and taxation policies, as well as possible political, economic, and market risks. These risks are heightened for investments in emerging markets which are also subject to greater illiquidity and volatility than developed foreign markets. This commentary is for information purposes only. It is a marketing communication and does not constitute investment advice or a recommendation to any reader of this content to buy or sell investments nor should it be regarded as investment research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. This document is not contractually binding nor are we required to provide this to you by any legislative provision.
All data from HSBC Asset Management unless otherwise specified. Any third-party information has been obtained from sources we believe to be reliable, but which we have not independently verified.
HSBC Asset Management is the brand name for the asset management business of HSBC Group, which includes the investment activities that may be provided through our local regulated entities. HSBC Asset Management is a group of companies in many countries and territories throughout the world that are engaged in investment advisory and fund management activities, which are ultimately owned by HSBC Holdings Plc. (HSBC Group).
- In Australia, this document is issued by HSBC Bank Australia Limited ABN 48 006 434 162, AFSL 232595, for HSBC Global Asset Management (Hong Kong) Limited ARBN 132 834 149 and HSBC Global Asset Management (UK) Limited ARBN 633 929 718. This document is for institutional investors only and is not available for distribution to retail clients (as defined under the Corporations Act). HSBC Global Asset Management (Hong Kong) Limited and HSBC Global Asset Management (UK) Limited are exempt from the requirement to hold an Australian financial services license under the Corporations Act in respect of the financial services they provide. HSBC Global Asset Management (Hong Kong) Limited is regulated by the Securities and Futures Commission of Hong Kong under the Hong Kong laws, which differ from Australian laws. HSBC Global Asset Management (UK) Limited is regulated by the Financial Conduct Authority of the United Kingdom and, for the avoidance of doubt, includes the Financial Services Authority of the United Kingdom as it was previously known before 1 April 2013, under the laws of the United Kingdom, which differ from Australian laws;
- In Bermuda, this document is issued by HSBC Global Asset Management (Bermuda) Limited, of 37 Front Street, Hamilton, Bermuda which is licensed to conduct investment business by the Bermuda Monetary Authority;
- In France, Belgium, Netherlands, Luxembourg, Portugal, Greece, Finland, Norway, Denmark, Spain and Sweden this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026);
- In Germany, this document is issued by HSBC Global Asset Management (Deutschland) GmbH which is regulated by BaFin (German clients) respective by the Austrian Financial Market Supervision FMA (Austrian clients);
- In Hong Kong, this document is issued by HSBC Global Asset Management (Hong Kong) Limited, which is regulated by the Securities and Futures Commission. This content has not been reviewed by the Securities and Futures Commission;
- In India, this document is issued by HSBC Asset Management (India) Pvt Ltd. which is regulated by the Securities and Exchange Board of India;
- In Italy, this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026), through its Italian branch, regulated by Banca d’Italia and Commissione Nazionale per le Società e la Borsa (Consob);
- In Japan, this document is issued by HSBC Asset Management (Japan) Ltd (JRN 3010001124868), regulated by the Financial Services Agency;
- In Malta, this document is issued by HSBC Global Asset Management (Malta) Limited which is regulated and licensed to conduct Investment Services by the Malta Financial Services Authority under the Investment Services Act;
- In Mexico, this document is issued by HSBC Global Asset Management (Mexico), SA de CV, Sociedad Operadora de Fondos de Inversión, Grupo Financiero HSBC which is regulated by Comisión Nacional Bancaria y de Valores;
- In the United Arab Emirates, this document is issued by HSBC Investment Funds (Luxembourg) S.A. – Dubai Branch (Level 20, HSBC Tower, PO Box 66, Downtown Dubai, United Arab Emirates) regulated by the Capital Market Authority (CMA) in the UAE to conduct investment fund management, portfolios management, fund administration activities (CMA Category 2 license No.20200000336) and promotion activities (CMA Category 5 license No.20200000327).
- In the United Arab Emirates, this document is issued by HSBC Global Asset Management MENA, a unit within HSBC Bank Middle East Limited, U.A.E Branch, PO Box 66 Dubai, UAE, regulated by the Central Bank of the U.A.E. and the Capital Market Authority in the UAE under CMA license number 602004 for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority. HSBC Bank Middle East Limited is a member of the HSBC Group and HSBC Global Asset Management MENA are marketing the relevant product only in a sub-distributing capacity on a principal-to-principal basis. HSBC Global Asset Management MENA may not be licensed under the laws of the recipient’s country of residence and therefore may not be subject to supervision of the local regulator in the recipient’s country of residence. One of more of the products and services of the manufacturer may not have been approved by or registered with the local regulator and the assets may be booked outside of the recipient’s country of residence.
- In Singapore, this document is issued by HSBC Global Asset Management (Singapore) Limited, which is regulated by the Monetary Authority of Singapore. The content in the document/video has not been reviewed by the Monetary Authority of Singapore;
- In Switzerland, this document is issued by HSBC Global Asset Management (Switzerland) AG. This document is intended for professional investor use only. For opting in and opting out according to FinSA, please refer to our website; if you wish to change your client categorization, please inform us. HSBC Global Asset Management (Switzerland) AG having its registered office at Gartenstrasse 26, PO Box, CH-8002 Zurich has a licence as an asset manager of collective investment schemes and as a representative of foreign collective investment schemes. Disputes regarding legal claims between the Client and HSBC Global Asset Management (Switzerland) AG can be settled by an ombudsman in mediation proceedings. HSBC Global Asset Management (Switzerland) AG is affiliated to the ombudsman FINOS having its registered address at Talstrasse 20, 8001 Zurich. There are general risks associated with financial instruments, please refer to the Swiss Banking Association (“SBA”) Brochure “Risks Involved in Trading in Financial Instruments”;
- In Taiwan, this document is issued by HSBC Global Asset Management (Taiwan) Limited which is regulated by the Financial Supervisory Commission R.O.C. (Taiwan);
- In Turkiye, this document is issued by HSBC Asset Management A.S. Turkiye (AMTU) which is regulated by Capital Markets Board of Turkiye. Any information here is not intended to distribute in any jurisdiction where AMTU does not have a right to. Any views here should not be perceived as investment advice, product/service offer and/or promise of income. Information given here might not be suitable for all investors and investors should be giving their own independent decisions. The investment information, comments and advice given herein are not part of investment advice activity. Investment advice services are provided by authorized institutions to persons and entities privately by considering their risk and return preferences, whereas the comments and advice included herein are of a general nature. Therefore, they may not fit your financial situation and risk and return preferences. For this reason, making an investment decision only by relying on the information given herein may not give rise to results that fit your expectations.
- In the UK, this document is issued by HSBC Global Asset Management (UK) Limited, which is authorised and regulated by the Financial Conduct Authority;
- In the US, this document is issued by HSBC Securities (USA) Inc., an HSBC broker dealer registered in the US with the Securities and Exchange Commission under the Securities Exchange Act of 1934. HSBC Securities (USA) Inc. is also a member of NYSE/FINRA/SIPC. HSBC Securities (USA) Inc. is not authorized by or registered with any other non-US regulatory authority. The contents of this document are confidential and may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose without prior written permission.
- In Chile, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Chilean inspections or regulations and are not covered by warranty of the Chilean state. Obtain information about the state guarantee to deposits at your bank or on www.cmfchile.cl;
- In Colombia, HSBC Bank USA NA has an authorized representative by the Superintendencia Financiera de Colombia (SFC) whereby its activities conform to the General Legal Financial System. SFC has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Colombia and is not for public distribution;
- In Costa Rica, the Fund and any other products or services referenced in this document are not registered with the Superintendencia General de Valores (“SUGEVAL”) and no regulator or government authority has reviewed this document, or the merits of the products and services referenced herein. This document is directed at and intended for institutional investors only.
- In Peru, HSBC Bank USA NA has an authorized representative by the Superintendencia de Banca y Seguros in Perú whereby its activities conform to the General Legal Financial System - Law No. 26702. Funds have not been registered before the Superintendencia del Mercado de Valores (SMV) and are being placed by means of a private offer. SMV has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Perú and is not for public distribution;
- In Uruguay, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Uruguayan inspections or regulations and are not covered by warranty of the Uruguayan state. Further information may be obtained about the state guarantee to deposits at your bank or on https://www.bcu.gub.uy/.
Copyright © HSBC Global Asset Management Limited 2026. All rights reserved. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of HSBC Asset Management.
Content ID: D079798; Expiry Date: 31.03.2027