NAV Finance and the Real Economy
SUMMARY
NAV finance is evolving into a mainstream Institutional asset class, combining potentially attractive risk-adjusted returns, robust structural protections and increasingly established governance standards. By providing capital to support growth and value creation within private market portfolios, NAV finance can help channel Institutional capital into the real economy. As adoption broadens and the market matures, NAV finance is well positioned to become a core component of private credit and asset-backed finance allocations, offering investors diversification and resilience.
The commentary and analysis presented in this document reflect the opinion of HSBC Asset Management on the markets, according to the information available to date. They do not constitute any kind of commitment from HSBC Asset Management. Consequently, HSBC Asset Management will not be held responsible for any investment or disinvestment decision taken on the basis of the commentary and/or analysis in this document. The views expressed above were held at the time of preparation and are subject to change without notice. The level of yield is not guaranteed and may rise or fall in the future. Diversification does not ensure a profit or protect against loss.
Based on an article published by Financial Investigator “Issue 6”: “NAV Finance and the Real Economy”, 11 October 2026.
Net asset value (NAV) finance, a long-established form of senior secured lending against the value of a private investment portfolio, has been provided by Banks for decades, and more recently by non-Bank lenders. The underlying use case typically is to finance growth within existing private asset portfolios, i.e. capital injected back into operating businesses poised for growth, and into the real economy.
The scale of adoption of NAV finance by Private asset owners, Private Equity GPs, and LPs has accelerated, supported by Institutional capital, rating agencies guidance and disclosure frameworks provided by ILPA.
A combination of potentially attractive returns, resilient credit profile and diversification make NAV finance a core part of any Asset Backed Finance portfolio for Institutional investors, namely insurance companies, pension funds and large family offices.
The NAV finance market is over USD 100 billion today and is expected to reach approximately USD 600 billion by 2030,1 mirroring the adoption trajectory of more traditional fund finance products such as subscription line facilities, and creating a clear investment opportunity for Institutional investors to build-out core private credit and Asset-backed financing portfolio allocations.
Financing growth and the real economy
As the private equity industry has matured and hold periods have extended, NAV financing has become an efficient and non-dilutive means for mid-market GPs to drive growth, whether organically, as part of a buy-and-build strategy, or by providing capital to acquire new portfolio companies, typically outside of the investment period. It is used by both GPs and LPs to support value creation objectives.
A clear differentiating factor within the NAV Finance market relates to the intended use of proceeds, and the facility structure. More than 80 per cent of NAV financings support portfolio investment1: bolt-on acquisitions, follow-on capital for existing holdings, new platform investments and the selective refinancing of performing assets. This capital is deployed back into operating businesses at a point in the Fund lifecycle where LP capital has been fully called, yet there remains further value creation opportunity.
Diversifying existing Private Credit and Asset-Backed financing allocations across institutional portfolios
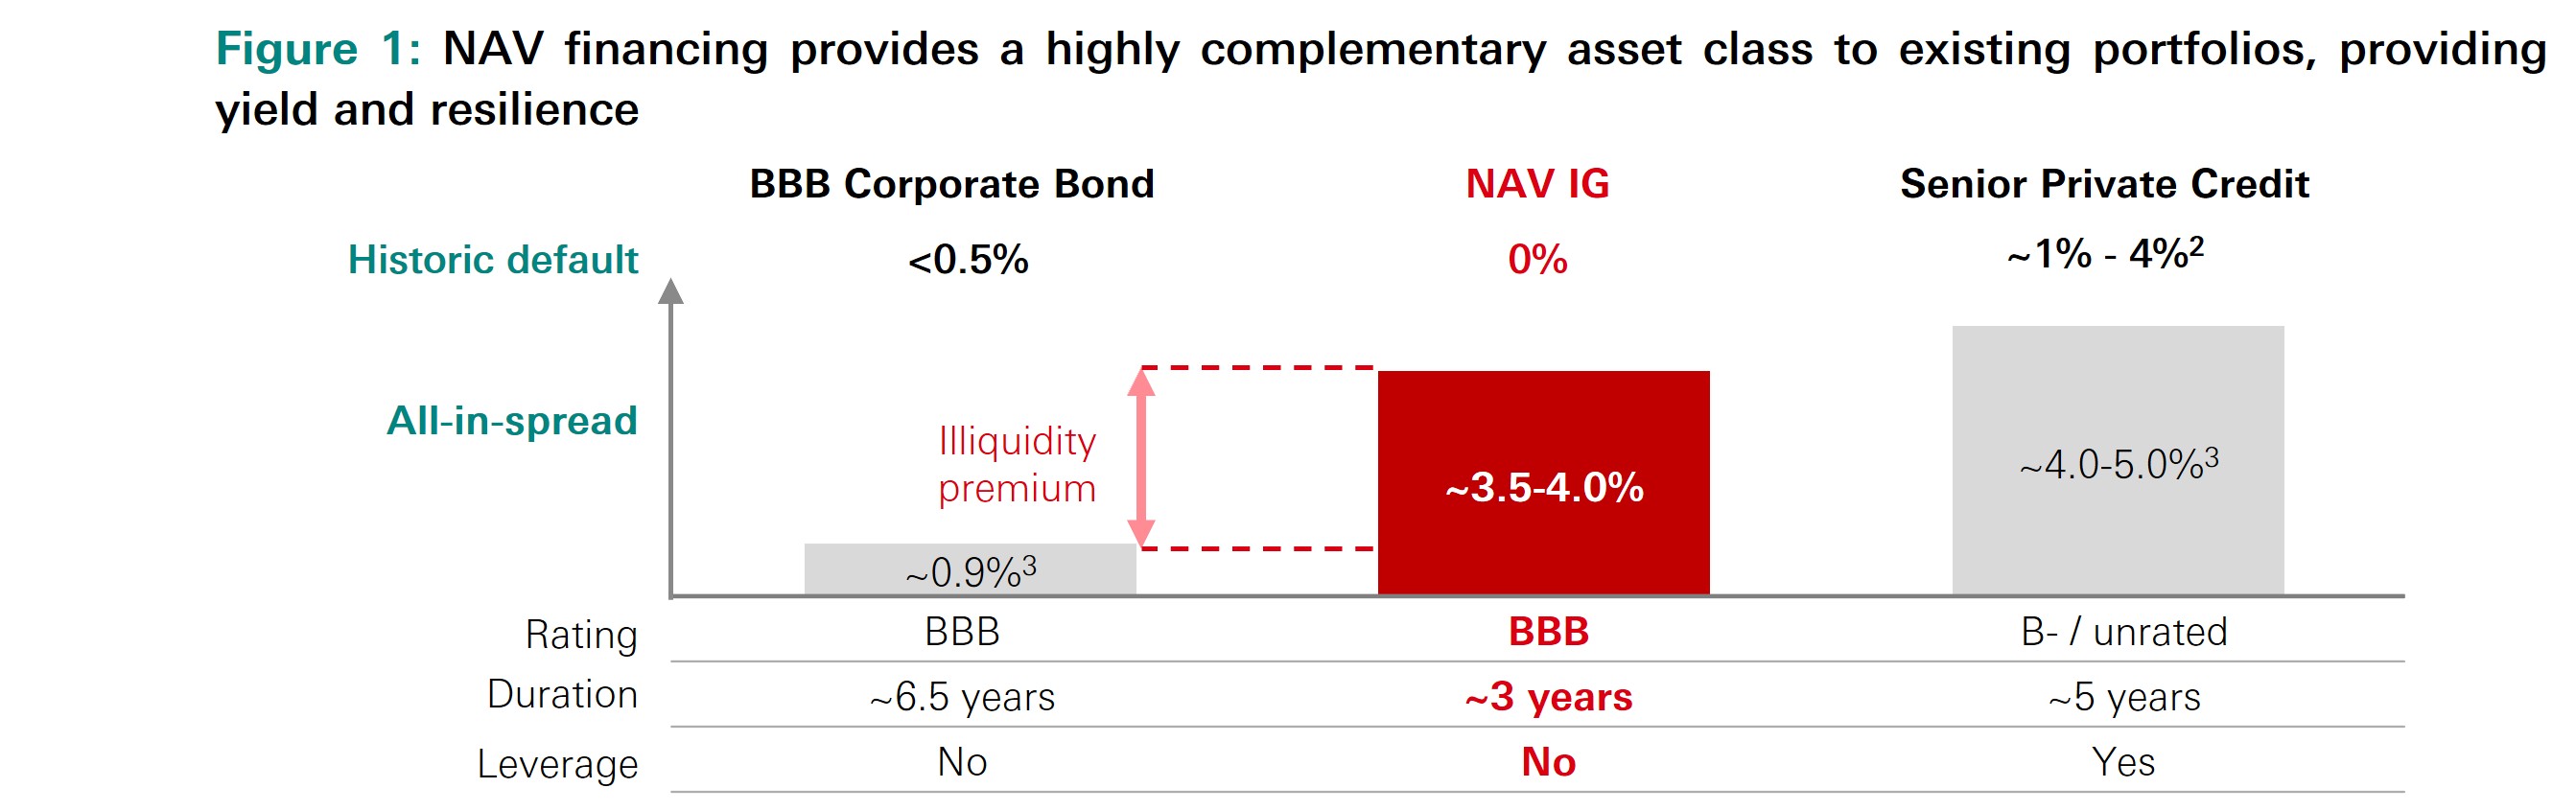
NAV finance strategies which invest in senior, investment-grade rated loans secured against portfolio assets can provide attractive excess spreads, similar to many sub-IG strategies, with a shorter maturity and an external agency IG-credit rating profile, with collateral diversification.
Click the image to enlarge
Source: HSBC Asset Management 2, 3
This positions NAV finance strategies as a potentially compelling proposition for investors requiring a sizeable IG-rated allocation or within Asset Backed Financing portfolios, capturing the illiquidity premium in an efficient format, without extending duration.
High quality credit
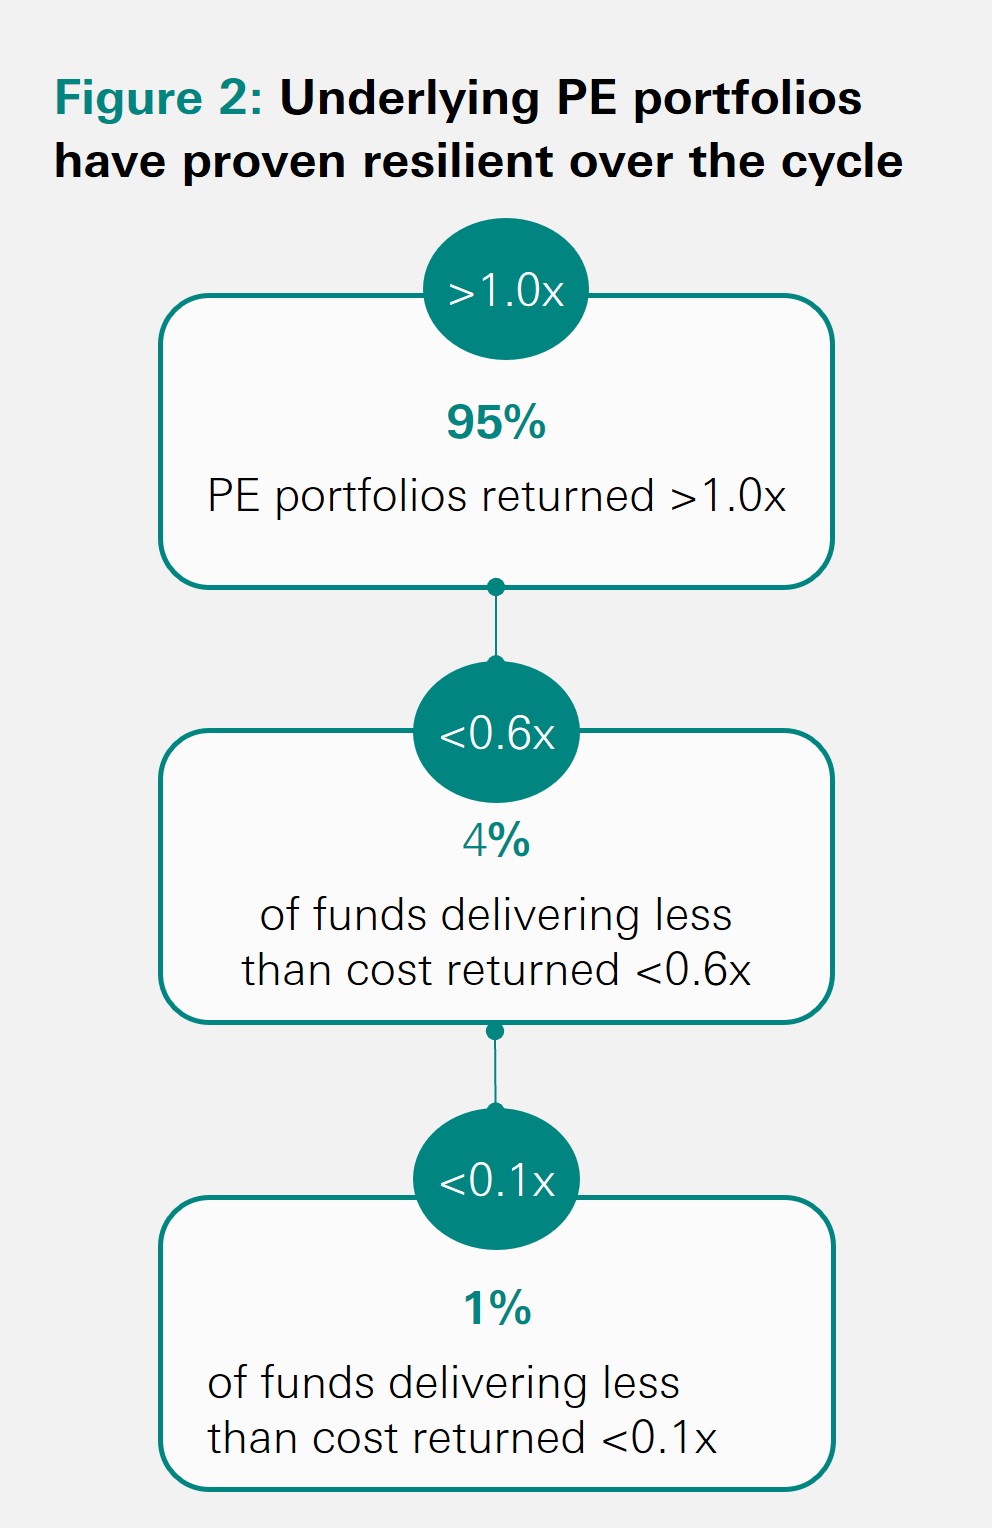
The combination of modest economic growth and increased macro and interest rate volatility tends to lead to an increased investor focus on asset classes with robust credit protections and proven resilience over the economic cycle.
NAV facilities structured as senior secured credit, contain protections that are cumulative rather than reliant on any single feature. Loan-to-value is typically in the 10-15 per cent range, reducing impairment risk and creating alignment with equity owners. Lending is cross collateralised across diversified, seasoned and performing asset portfolios, with no single asset exposure. Creditor-friendly waterfalls are designed to ensure priority access to cashflows and repayment ahead of distributions, while covenant packages combine loan-to-value tests, diversification requirements and cash sweep mechanisms.
Click the image to enlarge
Source: HSBC Asset Management4
Institutionalisation of NAV finance
The combination of enhanced disclosure standards and rating agency participation have helped to transform NAV finance into a mainstream Institutional asset class.
Governance has developed as quickly as the market itself. In July 2024 the Institutional Limited Partners Association (ILPA) published a five-part guidance on NAV-based facilities, developed with member LPs and in consultation with GPs, lenders, law firms and rating agencies. It sets clear expectations for disclosure of leverage, its cost and transparency with regard to the use of proceeds.
Sophisticated LPs consider the use of NAV finance in their fund investments, and this guidance gives all stakeholders a common reference point. It also helps to address a question often asked of the product: IG-NAV loans are not a mechanism for funding dividends or carry, and are typically focused on portfolio growth financing.
In parallel, the major credit rating agencies have published frameworks for NAV facilities, and senior secured transactions are increasingly rated investment grade. For insurers, an investment grade rating at three-to-four-year duration is capital-efficient under Solvency II, while the floating rate nature of the loans helps to limit volatility.
Outlook
NAV finance is expected to establish itself as a key component of many Private Equity Fund capital structures. It is a distinct exposure, driven by aggregate portfolio value and structural protections - supporting its role as a resilient diversifier within Institutional Private Credit / Asset Backed Financing portfolio allocations. NAV finance provides an opportunity to channel Institutional capital into a part of the real economy that remains underserved.
1ILPA guidance published Jul’24
2 L7Y average defaults (excluding and including Selected Defaults) – Source: S&P Global Ratings, July 2025
3 Bloomberg (EUR BBB Composite BVAL Index), Middle Market Leveraged Finance Report – Q1 2026 (Capstone Partners).
4 Preqin 1995 -2023 data
Important information
For Professional Clients and intermediaries within countries and territories set out below; and for Institutional Investors and Financial Advisors in the US. This document should not be distributed to or relied upon by Retail clients/investors.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. The performance figures contained in this document relate to past performance, which should not be seen as an indication of future returns. Future returns will depend, inter alia, on market conditions, investment manager’s skill, risk level and fees. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries and territories with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries and territories in which they trade.
The contents of this document may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. All non-authorised reproduction or use of this document will be the responsibility of the user and may lead to legal proceedings. The material contained in this document is for general information purposes only and does not constitute advice or a recommendation to buy or sell investments. Some of the statements contained in this document may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. We do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed herein are those of HSBC Asset Management at the time of preparation and are subject to change at any time. These views may not necessarily indicate current portfolios' composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients' objectives, risk preferences, time horizon, and market liquidity. Foreign and emerging markets: investments in foreign markets involve risks such as currency rate fluctuations, potential differences in accounting and taxation policies, as well as possible political, economic, and market risks. These risks are heightened for investments in emerging markets which are also subject to greater illiquidity and volatility than developed foreign markets. This commentary is for information purposes only. It is a marketing communication and does not constitute investment advice or a recommendation to any reader of this content to buy or sell investments nor should it be regarded as investment research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. This document is not contractually binding nor are we required to provide this to you by any legislative provision.
All data from HSBC Asset Management unless otherwise specified. Any third-party information has been obtained from sources we believe to be reliable, but which we have not independently verified.
HSBC Asset Management is the brand name for the asset management business of HSBC Group, which includes the investment activities that may be provided through our local regulated entities. HSBC Asset Management is a group of companies in many countries and territories throughout the world that are engaged in investment advisory and fund management activities, which are ultimately owned by HSBC Holdings Plc. (HSBC Group).
- In Australia, this document is issued by HSBC Bank Australia Limited ABN 48 006 434 162, AFSL 232595, for HSBC Global Asset Management (Hong Kong) Limited ARBN 132 834 149 and HSBC Global Asset Management (UK) Limited ARBN 633 929 718. This document is for institutional investors only and is not available for distribution to retail clients (as defined under the Corporations Act). HSBC Global Asset Management (Hong Kong) Limited and HSBC Global Asset Management (UK) Limited are exempt from the requirement to hold an Australian financial services license under the Corporations Act in respect of the financial services they provide. HSBC Global Asset Management (Hong Kong) Limited is regulated by the Securities and Futures Commission of Hong Kong under the Hong Kong laws, which differ from Australian laws. HSBC Global Asset Management (UK) Limited is regulated by the Financial Conduct Authority of the United Kingdom and, for the avoidance of doubt, includes the Financial Services Authority of the United Kingdom as it was previously known before 1 April 2013, under the laws of the United Kingdom, which differ from Australian laws;
- In Bermuda, this document is issued by HSBC Global Asset Management (Bermuda) Limited, of 37 Front Street, Hamilton, Bermuda which is licensed to conduct investment business by the Bermuda Monetary Authority;
- In France, Belgium, Netherlands, Luxembourg, Portugal, Greece, Finland, Norway, Denmark, Spain and Sweden this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026);
- In Germany, this document is issued by HSBC Global Asset Management (Deutschland) GmbH which is regulated by BaFin (German clients) respective by the Austrian Financial Market Supervision FMA (Austrian clients);
- In Hong Kong, this document is issued by HSBC Global Asset Management (Hong Kong) Limited, which is regulated by the Securities and Futures Commission. This content has not been reviewed by the Securities and Futures Commission;
- In India, this document is issued by HSBC Asset Management (India) Pvt Ltd. which is regulated by the Securities and Exchange Board of India;
- In Italy, this document is issued by HSBC Global Asset Management (France), a Portfolio Management Company authorised by the French regulatory authority AMF (no. GP99026), through its Italian branch, regulated by Banca d’Italia and Commissione Nazionale per le Società e la Borsa (Consob);
- In Japan, this document is issued by HSBC Asset Management (Japan) Ltd (JRN 3010001124868), regulated by the Financial Services Agency;
- In Malta, this document is issued by HSBC Global Asset Management (Malta) Limited which is regulated and licensed to conduct Investment Services by the Malta Financial Services Authority under the Investment Services Act;
- In Mexico, this document is issued by HSBC Global Asset Management (Mexico), SA de CV, Sociedad Operadora de Fondos de Inversión, Grupo Financiero HSBC which is regulated by Comisión Nacional Bancaria y de Valores;
- In the United Arab Emirates, this document is issued by HSBC Investment Funds (Luxembourg) S.A. – Dubai Branch (Level 20, HSBC Tower, PO Box 66, Downtown Dubai, United Arab Emirates) regulated by the Capital Market Authority (CMA) in the UAE to conduct investment fund management, portfolios management, fund administration activities (CMA Category 2 license No.20200000336) and promotion activities (CMA Category 5 license No.20200000327).
- In the United Arab Emirates, this document is issued by HSBC Global Asset Management MENA, a unit within HSBC Bank Middle East Limited, U.A.E Branch, PO Box 66 Dubai, UAE, regulated by the Central Bank of the U.A.E. and the Capital Market Authority in the UAE under CMA license number 602004 for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority. HSBC Bank Middle East Limited is a member of the HSBC Group and HSBC Global Asset Management MENA are marketing the relevant product only in a sub-distributing capacity on a principal-to-principal basis. HSBC Global Asset Management MENA may not be licensed under the laws of the recipient’s country of residence and therefore may not be subject to supervision of the local regulator in the recipient’s country of residence. One of more of the products and services of the manufacturer may not have been approved by or registered with the local regulator and the assets may be booked outside of the recipient’s country of residence.
- In Singapore, this document is issued by HSBC Global Asset Management (Singapore) Limited, which is regulated by the Monetary Authority of Singapore. The content in the document/video has not been reviewed by the Monetary Authority of Singapore;
- In Switzerland, this document is issued by HSBC Global Asset Management (Switzerland) AG. This document is intended for professional investor use only. For opting in and opting out according to FinSA, please refer to our website; if you wish to change your client categorization, please inform us. HSBC Global Asset Management (Switzerland) AG having its registered office at Gartenstrasse 26, PO Box, CH-8002 Zurich has a licence as an asset manager of collective investment schemes and as a representative of foreign collective investment schemes. Disputes regarding legal claims between the Client and HSBC Global Asset Management (Switzerland) AG can be settled by an ombudsman in mediation proceedings. HSBC Global Asset Management (Switzerland) AG is affiliated to the ombudsman FINOS having its registered address at Talstrasse 20, 8001 Zurich. There are general risks associated with financial instruments, please refer to the Swiss Banking Association (“SBA”) Brochure “Risks Involved in Trading in Financial Instruments”;
- In Taiwan, this document is issued by HSBC Global Asset Management (Taiwan) Limited which is regulated by the Financial Supervisory Commission R.O.C. (Taiwan);
- In Turkiye, this document is issued by HSBC Asset Management A.S. Turkiye (AMTU) which is regulated by Capital Markets Board of Turkiye. Any information here is not intended to distribute in any jurisdiction where AMTU does not have a right to. Any views here should not be perceived as investment advice, product/service offer and/or promise of income. Information given here might not be suitable for all investors and investors should be giving their own independent decisions. The investment information, comments and advice given herein are not part of investment advice activity. Investment advice services are provided by authorized institutions to persons and entities privately by considering their risk and return preferences, whereas the comments and advice included herein are of a general nature. Therefore, they may not fit your financial situation and risk and return preferences. For this reason, making an investment decision only by relying on the information given herein may not give rise to results that fit your expectations.
- In the UK, this document is issued by HSBC Global Asset Management (UK) Limited, which is authorised and regulated by the Financial Conduct Authority;
- In the US, this document is issued by HSBC Securities (USA) Inc., an HSBC broker dealer registered in the US with the Securities and Exchange Commission under the Securities Exchange Act of 1934. HSBC Securities (USA) Inc. is also a member of NYSE/FINRA/SIPC. HSBC Securities (USA) Inc. is not authorized by or registered with any other non-US regulatory authority. The contents of this document are confidential and may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose without prior written permission.
- In Chile, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Chilean inspections or regulations and are not covered by warranty of the Chilean state. Obtain information about the state guarantee to deposits at your bank or on www.cmfchile.cl;
- In Colombia, HSBC Bank USA NA has an authorized representative by the Superintendencia Financiera de Colombia (SFC) whereby its activities conform to the General Legal Financial System. SFC has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Colombia and is not for public distribution;
- In Costa Rica, the Fund and any other products or services referenced in this document are not registered with the Superintendencia General de Valores (“SUGEVAL”) and no regulator or government authority has reviewed this document, or the merits of the products and services referenced herein. This document is directed at and intended for institutional investors only.
- In Peru, HSBC Bank USA NA has an authorized representative by the Superintendencia de Banca y Seguros in Perú whereby its activities conform to the General Legal Financial System - Law No. 26702. Funds have not been registered before the Superintendencia del Mercado de Valores (SMV) and are being placed by means of a private offer. SMV has not reviewed the information provided to the investor. This document is for the exclusive use of institutional investors in Perú and is not for public distribution;
- In Uruguay, operations by HSBC's headquarters or other offices of this bank located abroad are not subject to Uruguayan inspections or regulations and are not covered by warranty of the Uruguayan state. Further information may be obtained about the state guarantee to deposits at your bank or on www.bcu.gub.uy.
Copyright © HSBC Global Asset Management Limited 2026. All rights reserved. No part of this publication may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording, or otherwise, without the prior written permission of HSBC Asset Management.
Content ID: D077576 ; Expiry Date: 31.03.2027